

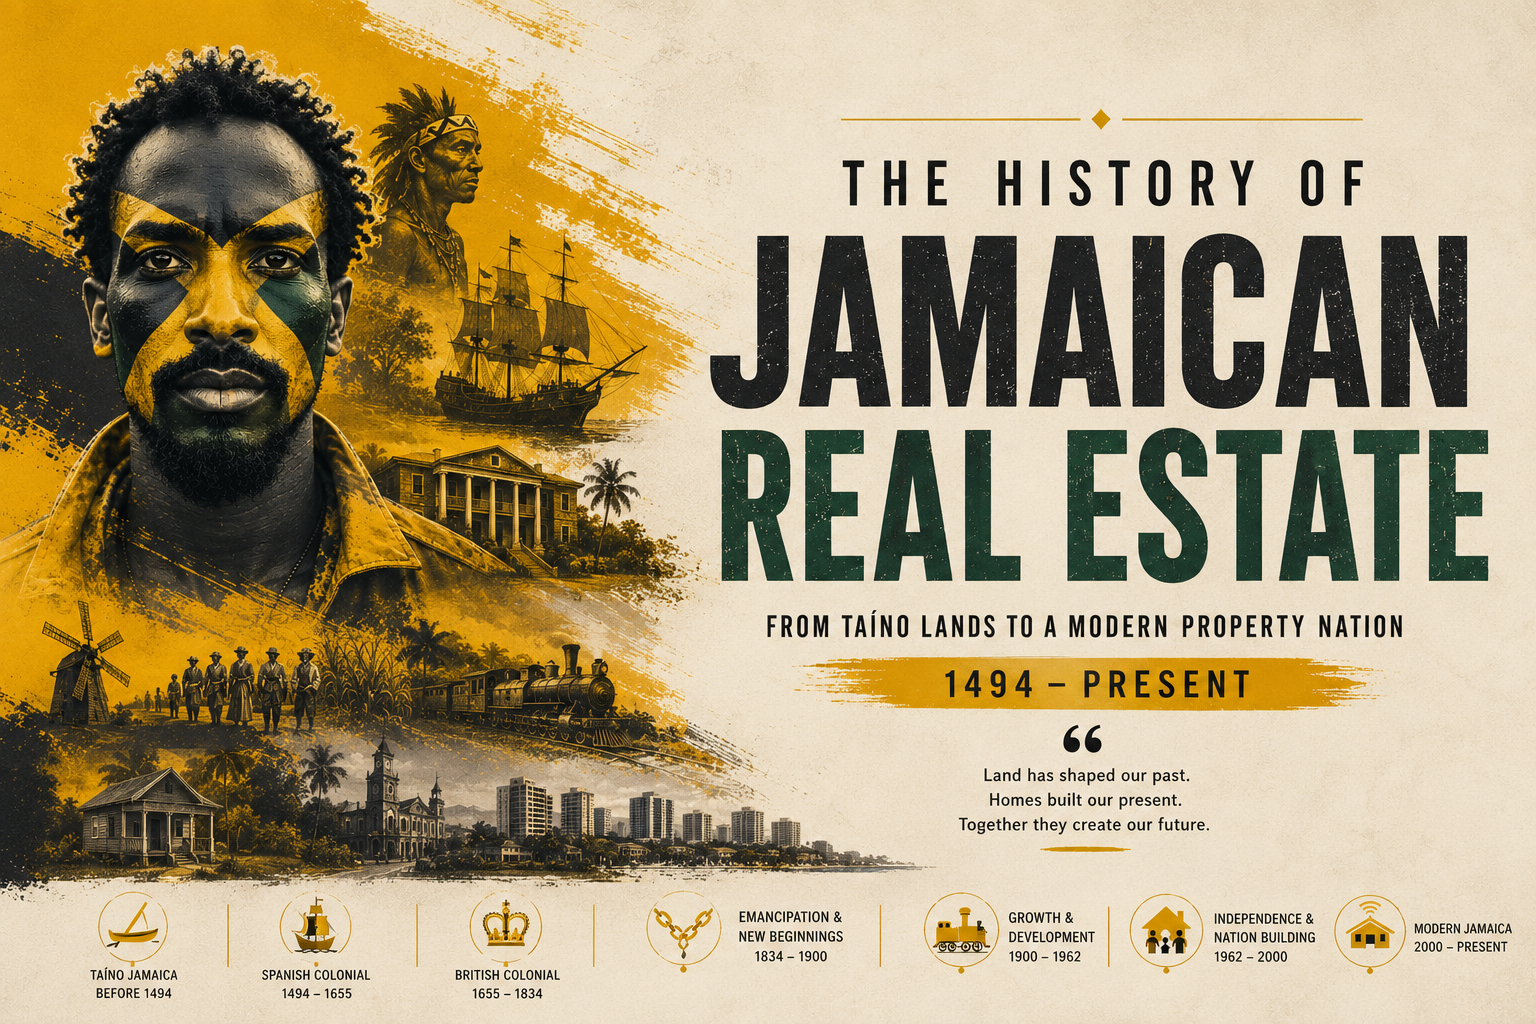
- Jamaica’s property tax roots trace to 1655 English conquest and quit rents.
- Jamaica uniquely taxed land value — not buildings — for centuries.
- 2013 reassessment triggered bills rising as much as 500 percent.
- Over 80 percent of potential property tax revenue goes uncollected.
- Parish councils depend on property tax as their primary revenue source.
- Reform debates pit value-based taxation against simpler area-based flat rates.
On a sun-scorched afternoon in the summer of 2013, Hyacinth Campbell spread three pieces of paper across her kitchen table in Stony Hill, St. Andrew. The first two were her property tax bills from the previous decade — modest sums she had paid without complaint. The third, freshly arrived from the Tax Administration Jamaica office, listed a figure she initially assumed was a printing error. Her annual liability had increased by more than four hundred percent. She was not alone. Across the island, from the hillside communities of Kingston to the cane fields of Westmoreland, Jamaicans opened envelopes and felt the ground shift beneath them.
That 2013 revolt — a political firestorm that forced a government climbdown and a parliamentary review — was not an isolated event. It was the latest chapter in a story that begins not in the twentieth century, not even in the nineteenth, but in the very first years of English colonial rule, when soldiers and planters carved up a Spanish colony and created a property regime that would cast its shadow across nearly four centuries of Jamaican life.
Conquest, Quit Rents, and the Birth of a Property Regime
When Admiral William Penn and General Robert Venables seized Jamaica from Spain in May 1655, they inherited an island virtually emptied of its indigenous Taino population and sparsely settled by Spanish colonists, most of whom fled to Cuba. The English Crown, eager to populate and profit from its new possession, faced an immediate problem: how do you finance colonial administration in a territory that produces almost nothing yet?
The answer arrived in the form of the quit rent, a medieval English device transplanted wholesale to the Caribbean. Land grants issued to soldiers, merchants, and adventurers came with an annual obligation — a payment to the Crown that substituted for the feudal military service that the name originally implied. In Jamaica, quit rents were typically set at a fixed rate per acre, regardless of whether that land was cultivated, forested, or lying idle under the blue mountains. Records held at the British National Archives at Kew confirm that by the 1670s, the system was already embedded in Jamaican title deeds, shaping the landscape of ownership for generations to come.
The quit rent was, in essence, the ancestor of the modern property tax: an annual levy on the right to hold land, paid to the sovereign authority. It established a principle that would persist in Jamaican law long after independence — that land ownership carries with it a fiscal obligation to the state, separate from any obligation arising from what one builds upon the land or earns from it.
Site Value Taxation: Jamaica’s Radical Inheritance
By the nineteenth century, Jamaica’s property tax had evolved into something philosophically distinctive: a system that taxed the unimproved value of land rather than the total value of the property including buildings. This approach, known as site value taxation or land value taxation, had powerful intellectual champions. The American economist Henry George, whose 1879 treatise Progress and Poverty argued that a single tax on land value could fund all government while eliminating poverty, was widely read in colonial Jamaica. His ideas found sympathetic ears among reformers who saw the great sugar estates and their absentee English owners as emblematic of an unjust order.
The practical effect of taxing land rather than buildings was significant: it penalized the holding of idle land and encouraged improvement. An owner who built a house, a factory, or a crop shed would not face higher taxes for doing so. The tax fell on the land itself — on its locational value, its proximity to roads and markets and community — and not on the productive effort of the owner. Scholars at the University of the West Indies (UWI) who have studied Jamaica’s fiscal history have noted that this approach was, in comparative terms, unusually progressive for its era. Most British colonial territories imported the metropole’s rate-based system, which taxed buildings heavily. Jamaica, for a variety of historical and administrative reasons, did not.
The Jamaica Assessment Review Department (JARD), the body responsible for property valuations, traces its institutional lineage to nineteenth-century assessors whose primary task was precisely this: to measure land, not structures. Assessment rolls from the 1880s and 1890s, some of which survive in the Jamaica Archives and Records Department in Spanish Town, show meticulous records of acreage and soil quality, with buildings noted as secondary information rather than primary tax bases.
Independence, Parish Councils, and the Revenue Question
Jamaica’s independence in 1962 brought new pressures on an old system. The new government of Prime Minister Alexander Bustamante inherited a property tax apparatus that was by most accounts inefficient, politically sensitive, and structurally inadequate to fund the services that an independent state was expected to provide. Yet property tax was also constitutionally linked to a structure of local government that neither the Jamaica Labour Party nor the People’s National Party wanted to dismantle: the parish councils.
Jamaica’s fourteen parishes — their boundaries largely unchanged from the colonial period — each maintained a parish council responsible for local roads, markets, poor relief, and basic sanitation. Under the arrangements inherited at independence and subsequently codified in Jamaican law, property tax revenues collected within each parish were earmarked for that parish’s council. This made property tax not merely a national revenue instrument but the financial lifeblood of local government. A parish that failed to collect its property taxes — or whose assessment roll was outdated — found its council literally unable to fill potholes or maintain public markets.
The National Land Agency (NLA), established in 2001 to consolidate various land administration functions, and the broader framework of the National Land Policy adopted in 1996, both acknowledged property tax as central to sustainable local governance. Documents published by the Jamaica Information Service (JIS) from the late 1990s repeatedly identify the modernization of property valuation and tax collection as a prerequisite for viable parish-level democracy.
The Assessment Crisis: Decades of Drift
Throughout the 1970s and 1980s, Jamaica’s property tax system drifted into what fiscal analysts would later describe as a state of structured neglect. Inflation eroded the real value of assessments that were not updated. Political pressure — on both sides of the partisan divide — discouraged reassessment exercises that would inevitably produce higher bills and angry voters. The result was an assessment roll that bore diminishing relationship to market reality.
By the early 1990s, economists studying the Jamaican fiscal system had begun documenting what they called the property tax gap: the difference between what the system should theoretically collect, based on the market value of land, and what it actually collected. Estimates varied, but a consensus emerged that Jamaica was collecting somewhere between fifteen and twenty cents for every dollar of potential property tax revenue. The tax gap, in other words, exceeded eighty percent.
This figure placed Jamaica among the most property-tax-deficient economies in the Caribbean and in the developing world more broadly. For context, well-functioning property tax systems in developed economies typically achieve collection ratios above eighty percent of assessed liability. Jamaica’s system was, in effect, operating in mirror image: it collected less than twenty percent while leaving more than eighty percent on the table.
The reasons were multiple and mutually reinforcing. Assessment rolls had not been comprehensively updated in some parishes for twenty years or more. Title registration was incomplete: large portions of the Jamaican property market operated through informal arrangements — what practitioners call “family land” — in which properties passed between generations through custom and community recognition rather than registered title. Unregistered land is, almost by definition, invisible to the property tax system. The National Land Agency and the Registrar General’s Department have both acknowledged that the gap between actual land holdings and formally registered titles remains one of the most persistent structural challenges in Jamaican property administration.
The Great Revolt of 2013
The 2013 reassessment exercise was, by any objective measure, long overdue. The Portia Simpson Miller administration, returned to power in the December 2011 general election, inherited a fiscal crisis of significant proportions, with Jamaica in extended negotiations with the International Monetary Fund over a structural adjustment programme. Property tax, chronically under-collected, was an obvious target for reform.
JARD conducted a comprehensive revaluation, updating assessments across the island to reflect something closer to contemporary market values. The arithmetic was inexorable: if land values had risen substantially since the last assessment — and in many cases they had risen by multiples — then tax bills would rise in proportion. In some communities, particularly in suburban and peri-urban areas around Kingston and Montego Bay that had seen rapid residential development, the increases were staggering. Bills that had previously run to a few thousand Jamaican dollars annually arrived in four or five-figure thousands or beyond. Some landowners reported increases of five hundred percent or more.
The political response was swift and fierce. Taxpayer associations organized. Letters flooded newspapers. Constituency representatives from both parties reported constituents in genuine financial distress. The Jamaica Gleaner and the Jamaica Observer ran front-page stories for weeks. What made the revolt particularly potent was that it cut across class lines: middle-class homeowners in Manor Park and Cherry Gardens were as aggrieved as small farmers in rural St. Elizabeth.
The government, facing the dual pressure of the IMF demanding revenue improvement and voters demanding relief, attempted a series of mitigating measures: payment plans, caps on year-over-year increases, hardship exemptions. Parliamentary debates on property tax during this period produced some of the more impassioned exchanges in recent Jamaican legislative history. Finance Minister Dr. Peter Phillips, defending the reassessment, argued that the alternative — continued under-collection — was fiscally unsustainable and fundamentally unfair to those who had been paying while others avoided assessment altogether. Opposition voices countered that the pace of increase was punitive and that implementation had been handled without adequate public communication.
Reform Proposals: The Debate That Would Not End
The 2013 crisis did what decades of academic commentary had failed to do: it forced a sustained public debate about the architecture of Jamaica’s property tax system. Two broad camps emerged, each with serious intellectual backing.
The first camp argued for doubling down on value-based taxation, modernizing the assessment process with satellite imaging, geographic information systems, and regular rolling revaluations rather than the periodic comprehensive exercises that had historically produced shock increases. Proponents, including several economists associated with UWI’s Department of Economics and the Caribbean Policy Research Institute (CaPRI), argued that this approach was the only one that captured the genuine economic value of land and maintained the progressive qualities of the Jamaican system’s long historical tradition. They pointed to the successful implementation of computer-assisted mass appraisal (CAMA) systems in other Caribbean jurisdictions as a model.
The second camp proposed moving toward an area-based flat rate system, under which tax liability would be calculated primarily from the physical size of a property rather than its market value. This approach, used in several Latin American countries and in parts of Eastern Europe, offers administrative simplicity and predictability: owners can calculate their bills without reference to contested valuations. Critics, however, noted that flat area-based taxes tend to be regressive — a small farmer in rural Clarendon and a resort hotel in Ocho Rios might pay similar per-acre rates despite wildly different economic circumstances. The National Land Policy working papers from the late 1990s had already identified this tension, though the 2013 crisis gave it renewed urgency.
A third position, advanced by some practitioners at the Jamaica Institute of Planners and in policy discussions at the NLA, proposed a hybrid: an area-based minimum floor combined with a value-based supplement for high-value properties. This approach has not been formally adopted but continues to circulate in policy discussions.
The Compliance Problem and the Informal Economy of Land
Behind the political drama of reassessment crises and reform debates lies a more intractable problem: the structural informality of much Jamaican land holding. The concept of “family land” — property passed down through families across generations without formal title transfer, often with multiple family members holding customary rather than legal rights — is deeply embedded in Jamaican rural society and has been extensively studied by anthropologists and legal scholars alike. Work by UWI researchers, drawing on the foundational studies of Edith Clarke and later scholars, has estimated that family land arrangements may govern a substantial minority of all rural land holdings in Jamaica.
For the property tax system, family land represents both a challenge and, in a certain sense, a mirror of historical injustice. These arrangements often originated in the post-emancipation period, when freed people who could not afford formal title registration developed community-recognized systems of tenure. The state never fully recognized these arrangements, and they remain outside the formal registration system administered by the Registrar General’s Department and recorded in the titles office maintained by the NLA.
Any genuine modernization of Jamaica’s property tax system must grapple with this reality. Tax collection agencies cannot collect from owners they cannot identify. Title regularization programmes — which have been attempted at various scales since the 1980s — are slow, expensive, and politically sensitive. The Jamaica National Heritage Trust (JNHT), while not directly involved in tax administration, has occasionally weighed in on aspects of land tenure history, noting the connection between historical patterns of dispossession and contemporary title deficiencies.
A History Inscribed in Deeds and Debts
Few aspects of Jamaican economic life are as revealing of the country’s layered history as its property tax system. In the quit rent records of the 1660s, one can trace the original distribution of plantation land to English adventurers. In the assessment rolls of the nineteenth century, one can see the emergence of a smallholder class purchasing fragments of former estates after emancipation. In the incomplete title registrations of the twentieth century, one can read the story of a society urbanizing faster than its institutions could adapt. And in the 2013 crisis, one can see all of these historical sediments colliding with a twenty-first-century fiscal emergency.
The property tax in Jamaica has never been merely a fiscal instrument. It has been a statement about who owns the island, what the state can demand of that ownership, and how the obligations of community are to be distributed across a society shaped by plantation agriculture, colonial administration, and post-colonial ambition. Every reform proposal, every assessment exercise, every collection drive reactivates these questions. They are not technical questions. They are political questions with technical dimensions, and they will not be resolved by spreadsheets alone.
As Jamaica continues to navigate the pressures of fiscal adjustment, local government modernization, and the chronic under-investment in parish infrastructure, the property tax will remain at the centre of the argument. The challenge for policymakers — and the lesson of three and a half centuries of fiscal history — is that a system so deeply entangled with land, identity, and power cannot be reformed by decree alone. It requires the kind of sustained political will and public deliberation that Jamaica’s property tax history has, to date, only rarely produced. The land is always there. The question is always who pays for the privilege of standing on it.
Follow Jamaica Homes on Youtube @jamaicahomes and Instagram @jamaica_homes and on Facebook @jamaicahomesnews Send us a message or email us at onlinefeedback@jamaica-homes.com or editor@jamaica-homes.com
Support independent Jamaican journalism.
- 1Our journalists cover housing, politics and community — stories that directly affect Jamaican lives.
- 2We have no billionaire owner and no advertisers calling the shots. Every story is decided by our editors.
- 3It costs less than a cup of coffee a week, and takes less time to subscribe than it took to read this article.
Support Jamaica Homes News today.
- Save 17% compared to monthly
- All articles unlocked
- Weekly newsletter
- Priority support
By subscribing you agree to our Privacy Policy and Terms.

Visit our YouTube Community ↗